
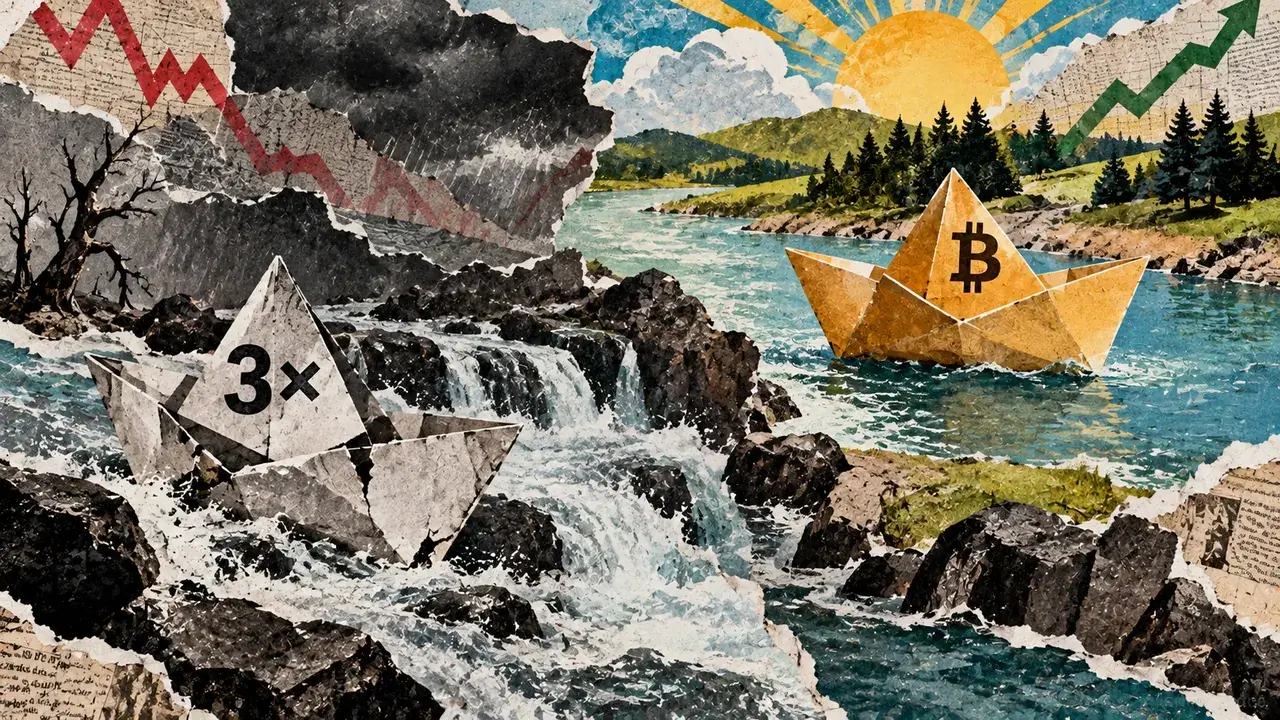
A Bitcoin investor can eventually be proven right about the direction of the market and still lose heavily through a daily-reset leveraged fund. That is the central risk highlighted by proposed 3x Bitcoin and Ethereum products moving closer to launch after a U.S. Securities and Exchange Commission listing approval.
According to CryptoSlate, the SEC approved exchange-listing rules on Oct. 2 for proposed funds from VS Trust. The products are designed to seek three times the daily return of their respective benchmarks, before fees and expenses. However, the daily target is not the same as delivering three times the return over a month, a year or the full period an investor holds the shares.
The distinction matters because leverage is recalculated every trading day. A fund can therefore produce a result that differs sharply from the performance of the underlying cryptocurrency over time, particularly when prices move up and down rather than advancing steadily.
Why daily leverage changes the outcome
Suppose Bitcoin falls sharply after an investor buys a leveraged fund. A 3x product is designed to lose roughly three times the benchmark’s daily decline, before costs. The fund’s assets are then smaller, and its exposure is adjusted around that reduced capital for the next session.
If Bitcoin later returns to its original price, the fund may not return to its original value. Losses incurred early in the holding period reduce the amount on which later gains are calculated. The fund can also reduce its market exposure after a decline, leaving it with a smaller position when a rebound begins.
The same mechanism can work in the other direction during a sustained rally. Gains increase the fund’s capital and can allow it to take on greater exposure in the following session. Depending on the path of prices, a daily-reset fund may outperform or underperform three times the benchmark’s cumulative move.
The SEC has previously illustrated the issue in an investor bulletin. In one four-month example involving an unnamed index, the index gained about 8%, while a fund seeking three times its daily return lost 53%. The example was not a Bitcoin fund and was not a forecast for VS Trust’s proposed products, but it demonstrates why a fund’s long-term result cannot be inferred simply by multiplying the underlying asset’s overall return.
The proposed products also warn that shareholders could lose their entire investment in one day or overnight. That warning reflects the possibility that a highly leveraged position can be overwhelmed by a sufficiently large move in the underlying market.
Futures and fees add more variables
The proposed funds would use Bitcoin and Ethereum futures rather than simply holding the cryptocurrencies. Futures are contracts with expiration dates, so a strategy seeking continued exposure must replace expiring contracts with later ones. The prices of those replacement contracts can either increase or reduce the cost of maintaining exposure, depending on the relationship between contracts for different delivery dates.
As a result, three times the change in Bitcoin’s spot price would not necessarily match the return of the Bitcoin fund. Futures-market effects, daily compounding, management fees and other expenses can all affect the result.
VS Trust’s amended filing dated Oct. 7 lists an annual management fee of 1.85% for both proposed products. The filing estimates that the Bitcoin fund would need a trading return of 1.98% and the Ethereum fund a return of 2.78% to cover estimated costs under its stated assumptions. Those are break-even estimates for the funds’ operating expenses, not returns investors are guaranteed to receive.
The products would also have a structure different from conventional investment-company ETFs governed by the Investment Company Act of 1940. The filings describe them as commodity-pool products and anticipate partnership tax reporting through Schedule K-1. Investors could receive taxable allocations without receiving corresponding cash distributions.
The listing approval is not a trading record
The SEC’s action creates a route for the products to reach an exchange, but it does not establish a performance history. The Oct. 7 filing said the funds had not begun trading, meaning there was no return record for the proposed Bitcoin product, identified as BITH, or the Ethereum product, identified as ETHK.
The structure may appeal to traders seeking amplified exposure without opening and managing a futures-margin account themselves. But the leverage remains embedded in the fund, and leaving the shares untouched does not convert a short-term daily product into a conventional long-term investment.
The key issue is the path taken by Bitcoin, not only its eventual destination. A volatile decline followed by a recovery can leave a daily-reset fund far below its starting value, even when the underlying cryptocurrency returns to its original price. The investor’s long-term conviction does not change the fund’s daily calculation or restore capital lost earlier.
Current market picture
Moneyiar data at 11:54 a.m. on Oct. 11, 2026, put Bitcoin at $83,063.436843442, up 0.3% over 24 hours but down 2.61% over seven days. Dai was priced at $0.9997367112, up 0.01% over 24 hours and 0.05% over seven days. Monad stood at $0.0256899437, gaining 4.09% in 24 hours while losing 23.34% over seven days. Ethereum Name Service was at $6.1303429295, down 3.42% over 24 hours and 9.61% over seven days.




