
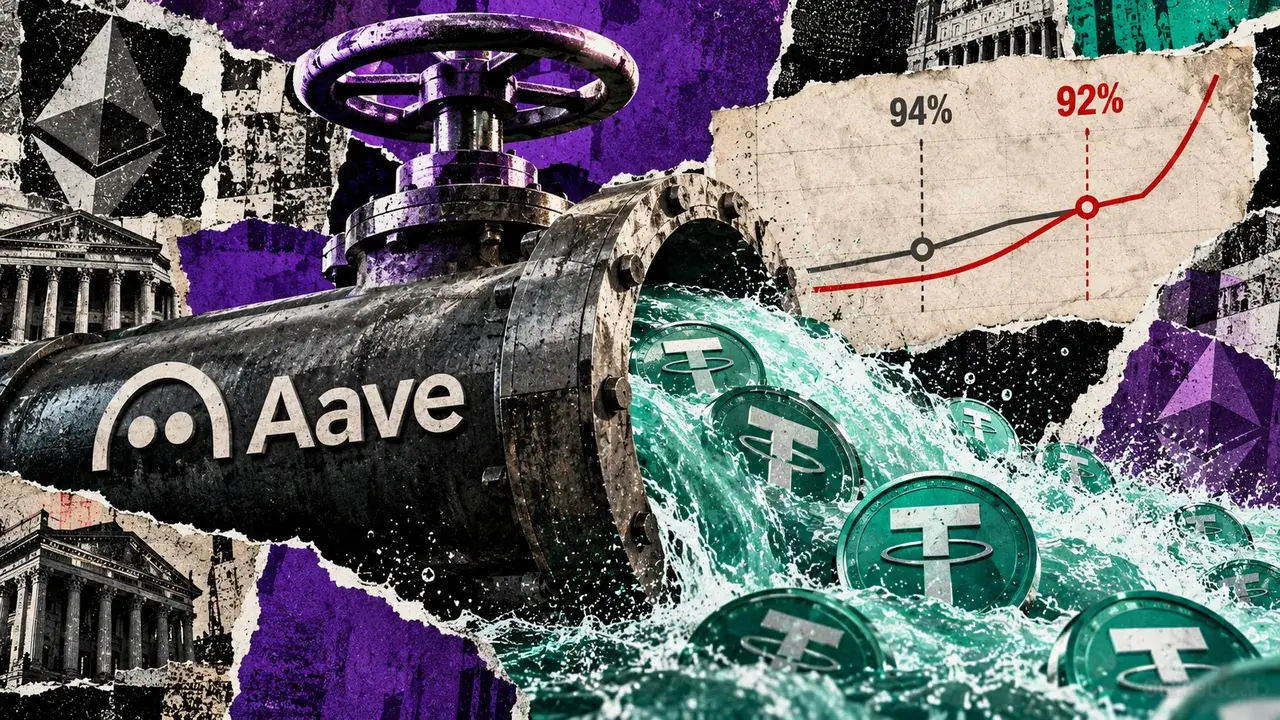
Aave has changed the interest-rate parameters for USDT borrowing on its Ethereum Core market, moving the point at which rates rise sharply from 94% to 92% utilization. The adjustment means borrowers face higher costs sooner when a larger share of the pool’s available liquidity is already being used.
According to CryptoSlate, the change was executed on Oct. 21 in Ethereum block 26,241,799. It does not prevent users from borrowing beyond 92% utilization. Instead, it shifts the market’s “kink”—the point where Aave’s two-slope interest-rate model begins increasing more aggressively—to a lower level.
The change is designed to preserve more withdrawal headroom in the lending pool as liquidity becomes tight. However, the additional liquidity implied by the model is not newly created cash. Whether funds are actually available for withdrawals still depends on repayments, new deposits, borrowing activity and withdrawals by other users.
How the new USDT rate curve works
Aave’s model raises borrowing rates gradually until the optimal utilization point. Above that point, rates increase at a steeper pace to encourage repayments and additional liquidity provision.
The deployed USDT parameters recorded at the Oct. 23 block were a 92% optimal usage ratio, a zero base rate, a 4.5% first slope and a 10% second slope. At the new kink, the borrowing rate is 4.5% annually. If utilization reached 100%, the rate under those parameters would be 14.5% annually.
The effect is clearest when comparing the old and new curves at the same utilization. At a hypothetical 94% utilization, the previous curve would have been exactly at its kink, producing a 4.5% borrowing APR. Under the new curve, 94% utilization is two percentage points above the 92% kink. Because the steeper portion covers eight percentage points, the modeled rate becomes 7%: 4.5% plus 10 percentage points multiplied by two-eighths.
That 7% figure is a conditional comparison, not the rate observed in the pool at that moment. The recorded USDT borrowing APR on Oct. 23 was about 4.23%.
For illustration, if a 1 million USDT loan remained unchanged for a full year and the modeled rates stayed at those levels, the 2.5 percentage-point difference would represent 25,000 USDT in additional simple annual interest. Actual costs can differ as utilization and rates change.
The modeled liquidity buffer is not cash in reserve
LlamaRisk, a DeFi risk service provider, reported 2,892.2 million USDT supplied in an Oct. 20 recommendation. Holding that supply constant, a pool operating at 94% utilization would have 6% unborrowed, while a pool at 92% utilization would have 8% unborrowed.
Those positions correspond to approximately 173.53 million USDT and 231.38 million USDT, respectively. The difference is 57.84 million USDT, or roughly 57.8 million USDT of additional modeled unborrowed liquidity at the lower threshold.
That figure describes two operating points on the same supplied balance. It does not mean Aave received 57.8 million USDT in new deposits or that the amount was automatically placed in the contract. LlamaRisk separately reported about 417 million USDT already idle when utilization was below either threshold.
The new curve can influence behavior: borrowers may repay or accept higher costs, while suppliers may be encouraged by improved returns to add liquidity. Yet the scale and timing of those responses are not fixed by the parameter change.
Borrowing rates, supplier returns and withdrawals
At block 26,254,517, timestamped Oct. 23 at 09:45:59 UTC, the reserve had approximately 2.9 billion USDT in outstanding supplier claims and 2.5 billion USDT in variable debt. The aToken contract held about 391.4 million USDT in physical tokens.
The same snapshot showed a variable borrowing APR of about 4.23% and a supplier liquidity APR of 3.29%. It also placed utilization at approximately 86.45% when debt was divided by debt plus the virtual accounting balance used by the interest-rate strategy—below the new 92% threshold.
The physical token balance and the virtual balance serve different purposes. The former represents tokens held by the contract, while the latter is an accounting input used to calculate pricing. The Oct. 23 snapshot is also separate from LlamaRisk’s Oct. 20 model and does not demonstrate that the parameter change caused any particular deposit, repayment or withdrawal.
Aave’s reserve factor was 10% in that snapshot, meaning part of borrowing interest was allocated to the protocol treasury before the supplier rate was calculated. Higher borrowing rates can raise the return offered to suppliers, but accrued interest is not the same as immediately withdrawable tokens.
Suppliers can withdraw only when sufficient unborrowed liquidity is available. Those using deposits as collateral may also need to repay debt or add collateral to maintain the health of their positions before withdrawing.
Current market picture
Moneyiar data at 08:18 on Oct. 24, 2026, shows Tether USDt at $0.9987677639, up 0.02% over 24 hours and 0.02% over seven days. AAVE was priced at $141.1717658359, down 5.44% over 24 hours and 9.71% over seven days.
The updated threshold therefore changes how Aave responds to tightening liquidity; it does not guarantee a particular cash balance or borrowing rate. The practical outcome will depend on how users alter borrowing, repayment, deposits and withdrawals as conditions in the USDT pool change.




