
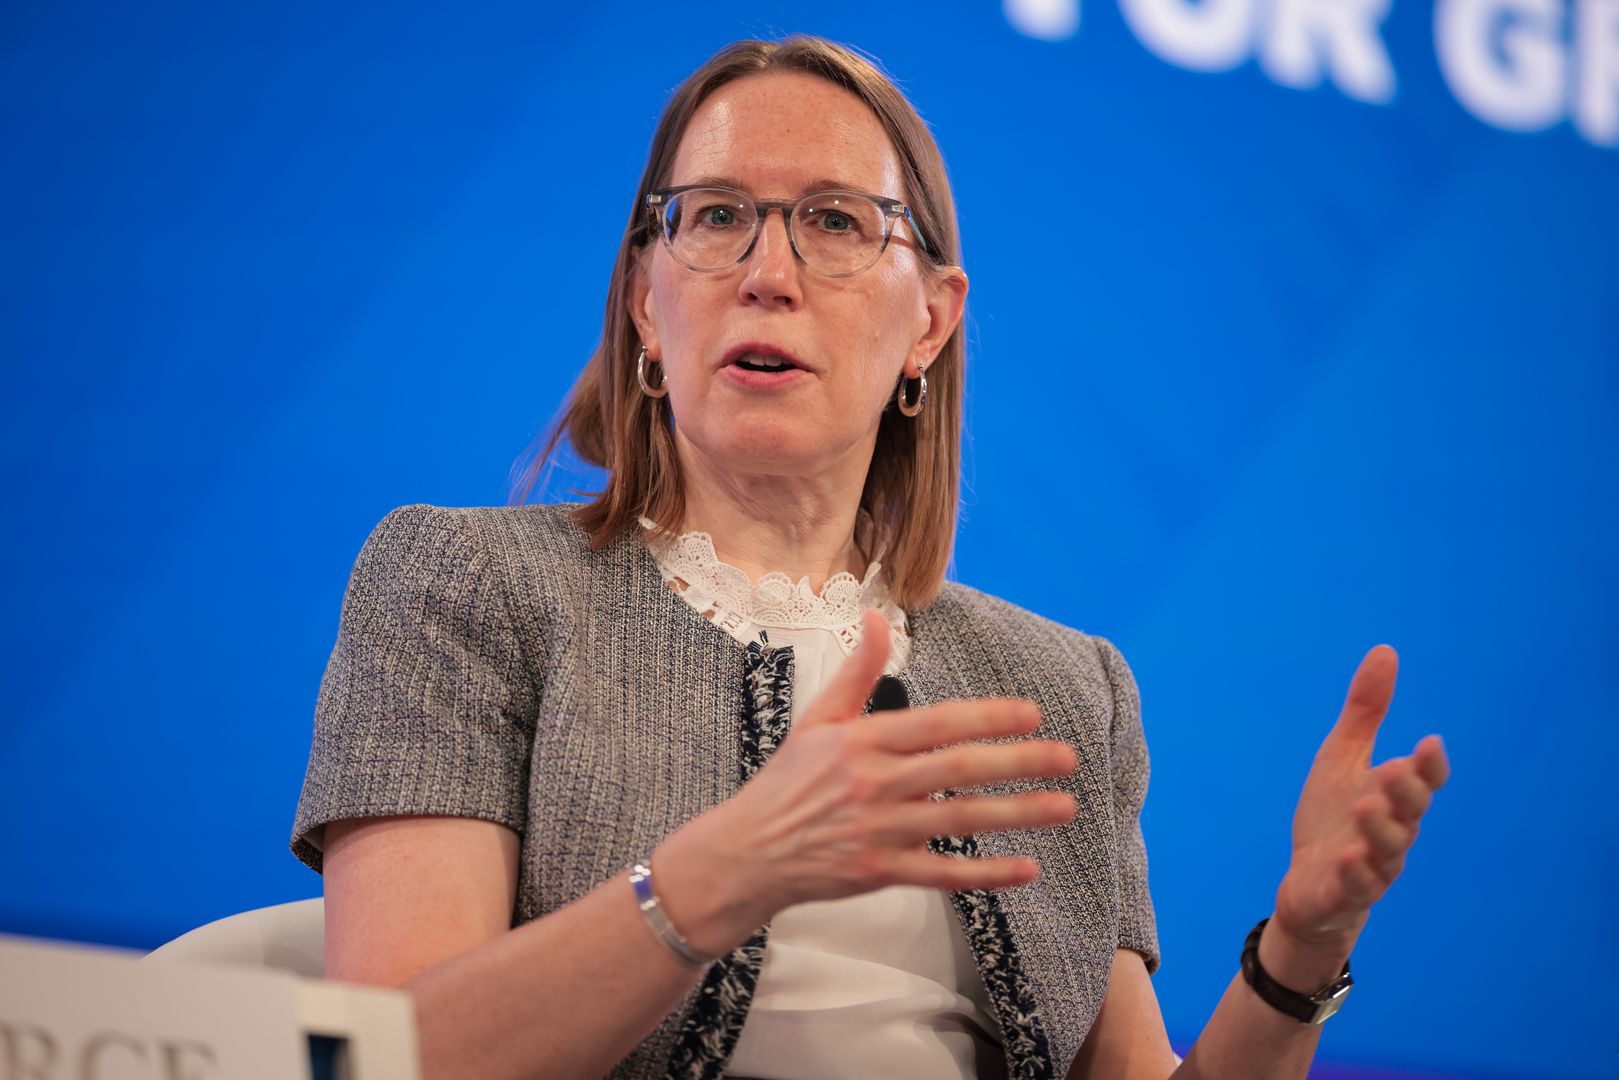
Hester Peirce’s departure from the U.S. Securities and Exchange Commission has prompted a call for policymakers and the digital-asset industry to continue her work on clearer crypto rules and stronger privacy protections.
Peirce’s final day as an SEC commissioner was described by Will Schwartz, a policy associate at the Blockchain Association, as the end of more than eight years of service by a prominent advocate for a rules-based approach to digital assets. In an opinion column published by CoinDesk, Schwartz praised Peirce for opposing enforcement actions when, in his view, the agency should instead have established rules that companies could follow.
The column presents Peirce’s departure as a turning point in a wider debate over how financial regulation should balance investor protection, law enforcement and individual privacy. It argues that the next phase of the discussion should focus not only on crypto markets, but also on the way financial systems collect, retain and use personal information.
Peirce’s record at the SEC
According to Schwartz, Peirce repeatedly dissented during the previous SEC chairman’s tenure when the commission chose enforcement over regulation. He also credits her with proposing a token safe harbor before regulators were ready to consider the idea and with leading the SEC’s Crypto Task Force.
A safe harbor generally refers to legal protection or a defined compliance path for activity that meets specified conditions. In the context described by the column, the proposal was intended to give digital-asset projects a clearer framework while allowing regulators to address investor-protection concerns.
Schwartz says Peirce viewed investor protection as requiring the SEC to use its authority to provide regulatory guardrails for a rapidly expanding industry. The article does not present her departure as the completion of that work. Instead, it argues that the policy questions she raised remain unresolved and will require action from others after she leaves the commission.
Peirce’s last public remarks as commissioner, delivered at SIFMA’s Digital Assets Conference on September 23, focused on what Schwartz calls a societal crossroads. One possible direction, according to the column, is continued expansion of surveillance and the collection of personal data. The alternative would seek to preserve privacy while still allowing people to demonstrate compliance with the law.
The privacy debate behind financial regulation
The column criticizes a financial-regulatory model that has relied for more than 50 years on collecting and storing personal information from people who use the financial system. Businesses gather data from consumers and share it with government authorities, which then seek evidence of criminal conduct within a much larger pool of information from people who are not suspected of wrongdoing.
Schwartz uses Peirce’s “needle” and “haystack” comparison to describe the problem: criminal activity is the needle, while the data of innocent consumers forms the haystack. The argument is that expanding the amount of information does not necessarily make the search more effective.
The article identifies several risks associated with centralized data stores. A breach can expose more information and cause greater harm when large amounts of consumer data are held in one place. Required disclosures can also contribute to the work of data brokers, which use public filings and records to create consumer profiles for commercial purposes. Schwartz further argues that broad surveillance can leave people vulnerable to censorship and discrimination, regardless of their political views.
The column says the challenge could grow as artificial intelligence becomes more integrated into everyday life. In its view, AI may collect more personal information and make surveillance and profiling more sophisticated. These claims are presented as part of Schwartz’s argument for changing the regulatory framework, rather than as a new SEC policy announced with Peirce’s departure.
Blockchain tools and the next policy test
Schwartz points to privacy-enhancing technologies associated with the blockchain ecosystem as a possible way to reduce unnecessary exposure of personal data without eliminating legal oversight.
Blockchain systems can record transactions publicly and securely while potentially allowing individuals to retain greater control over their information. Zero-knowledge proofs are cited as one example. They can allow a person to prove that they are authorized to carry out a transaction without revealing information that is not needed for that particular verification.
Verifiable credentials are another tool mentioned in the column. They can be used to demonstrate that an individual is genuine or meets a trust requirement without necessarily disclosing the person’s identity. In this model, compliance does not require every participant to reveal all of their personal details.
The central argument is that the technology already exists, but the rules needed to support its adoption do not. Schwartz calls for a modern regulatory framework that would let consumers control their data while still giving law-enforcement authorities the information needed to monitor transactions and pursue bad actors.
For the digital-asset industry, the debate matters because unclear regulation can shape whether privacy-focused systems are developed and used. For consumers, it concerns how much personal information must be surrendered to access financial services. Schwartz concludes that Peirce’s mission now passes to industry participants, policymakers and others who support combining privacy with security rather than treating one as the cost of achieving the other.
Moneyiar market picture
Moneyiar market data at 8:58-8:59 a.m. on October 3, 2026, showed mixed performance among the listed digital assets:
- Cronos (CRO) was trading at $0.0663426751, down 4.02% over 24 hours but up 0.68% over seven days.
- Polygon (prev. MATIC) (POL) stood at $0.1078365266, down 2.66% in 24 hours and 9.98% over seven days.
- ONEchain (ONE) was priced at $0.1407704502, up 1.62% over 24 hours but down 5.33% over seven days.




