
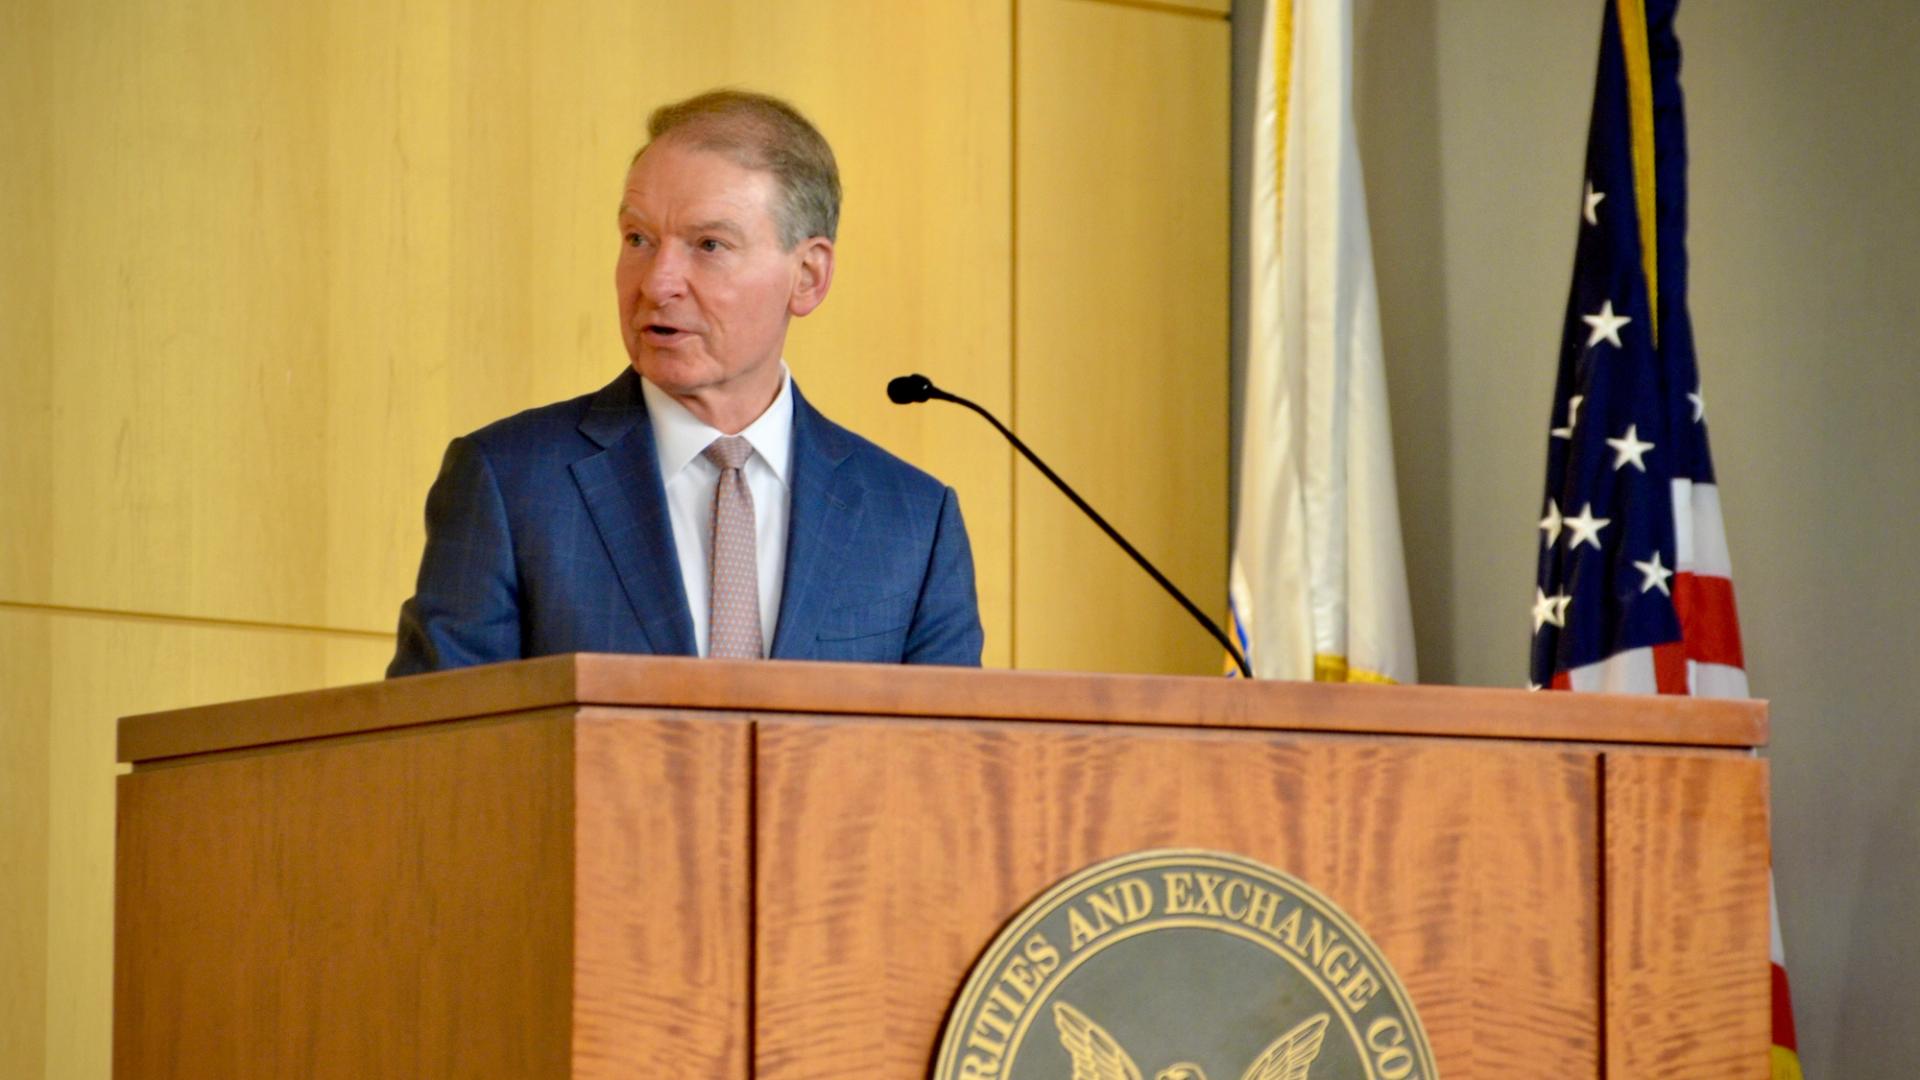
The U.S. Securities and Exchange Commission has proposed a new framework for the custody of crypto assets held for investment advisers’ clients and regulated funds, seeking to replace uncertainty around rules originally designed for traditional assets.
According to CoinDesk, the 760-page proposal would define which types of firms can hold digital assets, establish recordkeeping and federal disclosure requirements, and set expectations for industry practices and audits. It is the latest major step in the SEC’s broader effort to establish rules for the digital-asset market.
What the proposal would change
SEC Chairman Paul Atkins said the proposal would give investment advisers and funds a compliant route for handling crypto assets where no clear framework had previously existed. He said the existing custody regime was created to protect advisory clients and regulated funds against loss, theft, misuse and misappropriation, but was built around traditional assets rather than the characteristics of crypto markets.
Custody rules generally govern how client assets are held separately, monitored and protected. For investment advisers and funds, the identity and responsibilities of the custodian are central to that process. The SEC proposal would provide greater clarity on which companies could serve that role for crypto assets and how advisers and regulated funds would need to document and report their custody arrangements.
The agency also proposed allowing state-chartered trusts to act as crypto custodians. In addition, the text includes provisions covering industry practices and auditing, areas that can determine how firms demonstrate control over client assets and compliance with regulatory obligations.
The proposal will be open for public comment for 60 days. During that period, firms, investors and other interested parties can submit views before the SEC considers the next stage of the rulemaking process.
Limited route for adviser self-custody
One of the proposal’s notable features is a limited ability for an investment adviser to hold client crypto assets itself. The SEC is using “self-custody” in this context to describe an asset-management firm holding its clients’ funds, rather than the broader crypto meaning often associated with individuals or companies controlling assets without an outside custodian.
The option would not be generally available. An adviser would first have to show that it could not find a qualified custodian willing to hold the assets. The firm would also need to possess specified expertise in handling crypto assets. An SEC official said the adviser’s ability to retain custody would have to be reviewed every quarter to determine whether a suitable custodian had become available.
The official said such circumstances would probably be unusual once the rule was in place. One possible situation identified by the SEC would involve a newly launched token that established custodians did not yet support. The proposal therefore links self-custody to a lack of an available qualified provider rather than presenting it as a standard alternative to third-party custody.
Part of a wider SEC crypto agenda
The custody proposal follows two other recent SEC initiatives. Last month, the agency published its Innovation Exemption for the tokenization of securities, describing potential pathways for companies to place traditional securities products on a blockchain. In August, it issued its Reg Crypto proposal, which addressed how companies could raise funds using digital assets while complying with federal requirements.
The custody measure also comes as Commissioner Hester Peirce prepares to leave the SEC. Peirce, who has led the agency’s Crypto Task Force since it was created, is due to depart on Friday and become a professor in Virginia. Her departure will leave the commission with two members.
Earlier in the week, the SEC said it was reducing the number of commissioners needed for a quorum. The agency had previously required at least three commissioners; under the new approach, two will generally be sufficient. If one of those commissioners is unable to participate in a particular matter because of a conflict, the remaining commissioner can form a quorum.
The custody proposal marks another completed element of the major crypto topics identified by Atkins for the agency’s agenda. Its practical effect will depend on public comments and the SEC’s eventual action, but the document sets out a proposed structure for custody, disclosures, audits and the narrow circumstances in which advisers could retain client assets themselves.
Moneyiar market picture
Moneyiar data at the stated times show mixed performance among the selected crypto assets:
- FUNToken (FUN) was priced at $0.0083984912, up 1.34% over 24 hours and 5.97% over seven days, as of October 3, 2026, at 09:03 +03:30.
- ONEchain (ONE) stood at $0.1410178789, gaining 1.97% over 24 hours but falling 5.36% over seven days, as of October 3, 2026, at 09:04 +03:30.
- Propy (PRO) traded at $0.3623882289, down 0.70% over 24 hours and up 4.53% over seven days, as of October 3, 2026, at 02:04 +03:30.
- Ontology Gas (ONG) was $0.090510231, down 2.55% over 24 hours and 7.04% over seven days, as of October 3, 2026, at 09:03 +03:30.




