
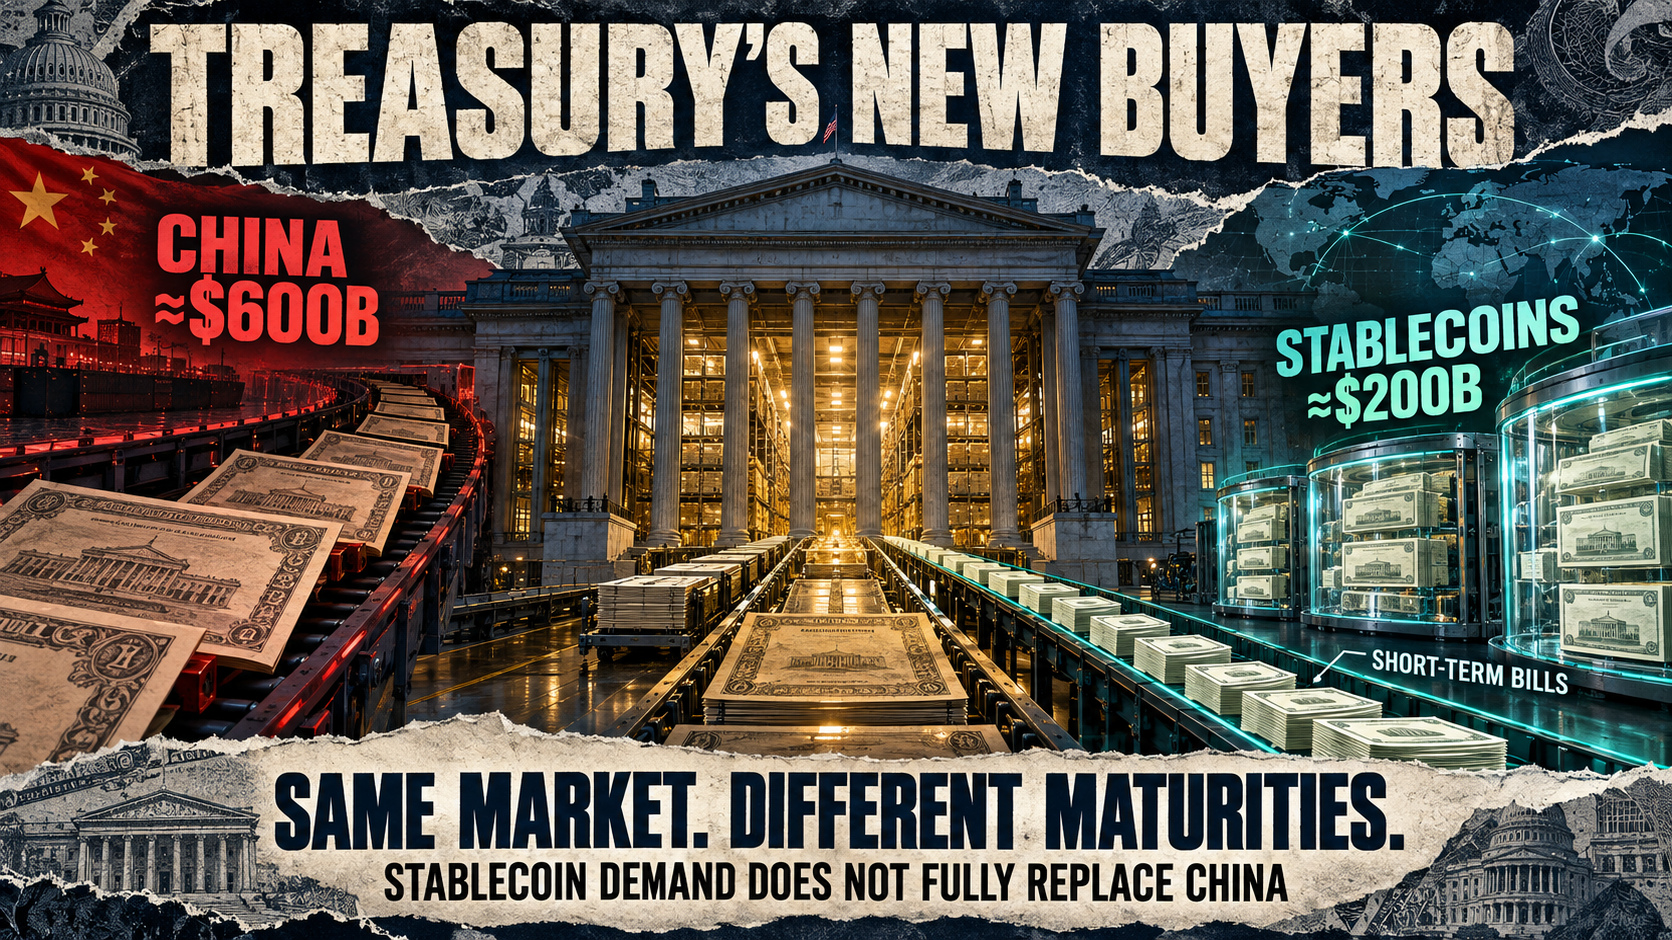
Stablecoin companies have become an increasingly important source of demand for US government debt, adding about $200 billion in Treasury securities and repurchase agreements over the past five years. That amount represents more than 40% of the decline in China’s holdings of US Treasuries during the same period, according to research from the Federal Reserve Bank of San Francisco cited by CryptoSlate.
A changing investor base for US debt
The shift reflects two developments moving in opposite directions. Tether and Circle, the issuers behind the USDT and USDC stablecoins, have expanded their reserve portfolios as demand for dollar-linked digital tokens has grown. Meanwhile, China has continued a reduction in its Treasury holdings that began more than a decade ago.
Stablecoins are digital tokens designed to maintain a value linked to an asset such as the US dollar. Issuers generally hold liquid assets against the tokens so customers can redeem them. Those reserves can include short-term Treasury securities, cash, bank deposits and repurchase agreements, which are short-term transactions backed by securities.
Stablecoin issuers’ Treasury holdings have increased more than tenfold in five years, giving them a substantially larger role in the short-term government debt market. Since 2023, they have added more short-term Treasury holdings than Japan, the largest foreign holder of US government debt, according to the San Francisco Fed research.
The broader investor base for Treasuries has also changed. Foreign investors held more than half of all outstanding Treasury securities around 2008, but their share had fallen to about 30% by early 2026. Foreign governments represented just above 40% of foreign Treasury demand by early 2026, compared with nearly all of it at their peak in the 1970s.
China’s Treasury holdings reached a peak in late 2013 and had dropped by more than half by mid-2026 as Beijing diversified its reserve assets. As official foreign demand has weakened, private investors have taken on a larger role. Unlike central banks managing reserves, private buyers may seek higher yields when perceptions of fiscal risk increase or other investments become more attractive.
Why stablecoins cannot fully replace China
The comparison with China has an important limitation: the two groups tend to buy different types of Treasury debt.
China’s reductions have been concentrated largely in longer-dated US government securities. Stablecoin issuers, by contrast, mainly purchase Treasury bills and other highly liquid assets with short maturities. Their growing reserves can therefore strengthen demand for short-term government borrowing without creating an equivalent buyer for longer-term notes and bonds.
That distinction matters as the US faces larger financing needs. Federal debt held by the public has risen from about 35% of gross domestic product in 2006 to roughly 100% today. The investor base available to absorb new issuance is consequently receiving greater attention.
US regulation may further direct stablecoin reserves toward short maturities. The GENIUS Act, adopted in 2025, established a federal framework requiring approved US payment stablecoin issuers to fully back outstanding tokens with eligible liquid reserves. Proposed implementing rules include Treasury bills, notes and bonds with remaining maturities of 93 days or less, as well as cash, bank deposits and certain Treasury-backed repurchase agreements.
This framework could link the expansion of regulated dollar stablecoins with additional demand for highly liquid US government securities. The structure can also generate income for issuers: customers generally do not receive the interest earned on the assets backing their tokens, while issuers can collect that income. As token circulation grows, reserve portfolios and associated interest revenue can increase as well.
Global adoption could increase Treasury-bill demand
The San Francisco Fed researchers said the future effect will depend partly on whether stablecoins attract users beyond traditional cryptocurrency trading. Stablecoins are increasingly used for cross-border payments and as dollar-denominated stores of value in countries where local currencies are volatile.
Usage relative to economic output is particularly high in Africa, the Middle East and Latin America, with much of the activity crossing national borders. When an overseas customer acquires a dollar stablecoin, the issuer takes on an additional reserve obligation and may purchase Treasury bills to back the token. In that way, a user outside the US can indirectly contribute to demand for US government debt.
If the industry maintains its recent growth rate, stablecoin issuers’ Treasury holdings could approach $400 billion by 2030, the Fed researchers estimated. They also stressed that the projection is highly uncertain. Regulation in other countries, competing digital-payment products and new banking technology could all limit adoption.
Banks developing less expensive cross-border settlement systems could capture some of the same activity. Stablecoin companies expanding into remittances and payments, meanwhile, would need to maintain larger liquid reserves as their circulation increases. The outcome will help determine how much future demand for dollar-based digital payments reaches the Treasury market.
Moneyiar market picture
Moneyiar data as of October 3, 2026, shows Tether USDt at $0.9997948518, effectively close to its dollar reference, with no 24-hour change and a 0.01% gain over seven days. Ethereum was priced at $2,682.7929680954, down 2.39% over 24 hours and up 0.07% over seven days.
The token listed as Stable was at $0.0266085356, down 5.97% over 24 hours but up 1.36% over seven days. Ailey stood at $0.2694329589, declining 0.17% in 24 hours and gaining 0.12% over seven days. These figures are Moneyiar market data recorded at approximately 09:38-09:39 +03:30.




