
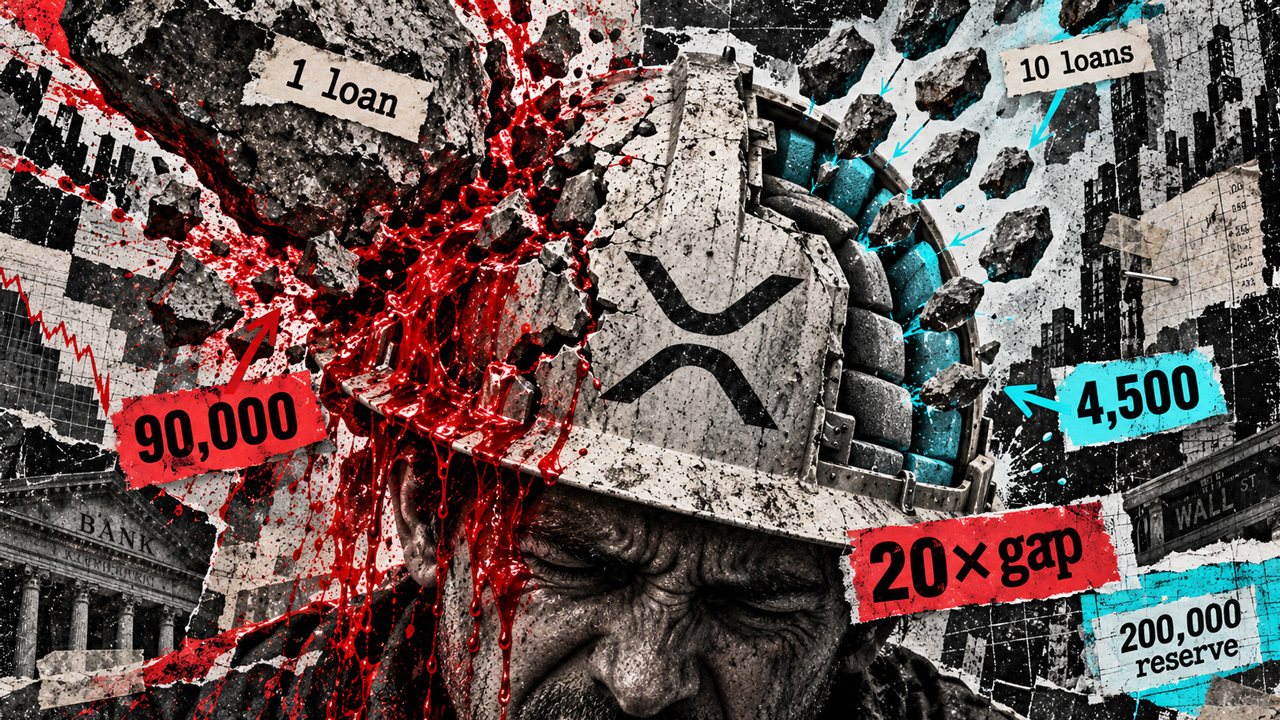
A modeled XRP lending scenario shows that reserve coverage alone may not prevent concentrated losses for vault depositors. According to CryptoSlate, a single default under the model would leave the vault with a 90,000-token loss, even though the reserves are twice the size of the bad loan. Depositors would absorb 90% of the loss. By contrast, spreading the same exposure across ten smaller loans would reduce the modeled vault loss to 4,500 tokens, using the same reserve and cover rates. The comparison highlights how loan concentration can materially affect outcomes in the model, despite identical stated coverage assumptions. The figures describe a modeled scenario rather than a reported market loss or confirmed default.
Source
CryptoSlate
Written by Moneyiar based on reporting from the cited source and Moneyiar market data.
Read original source ↗




